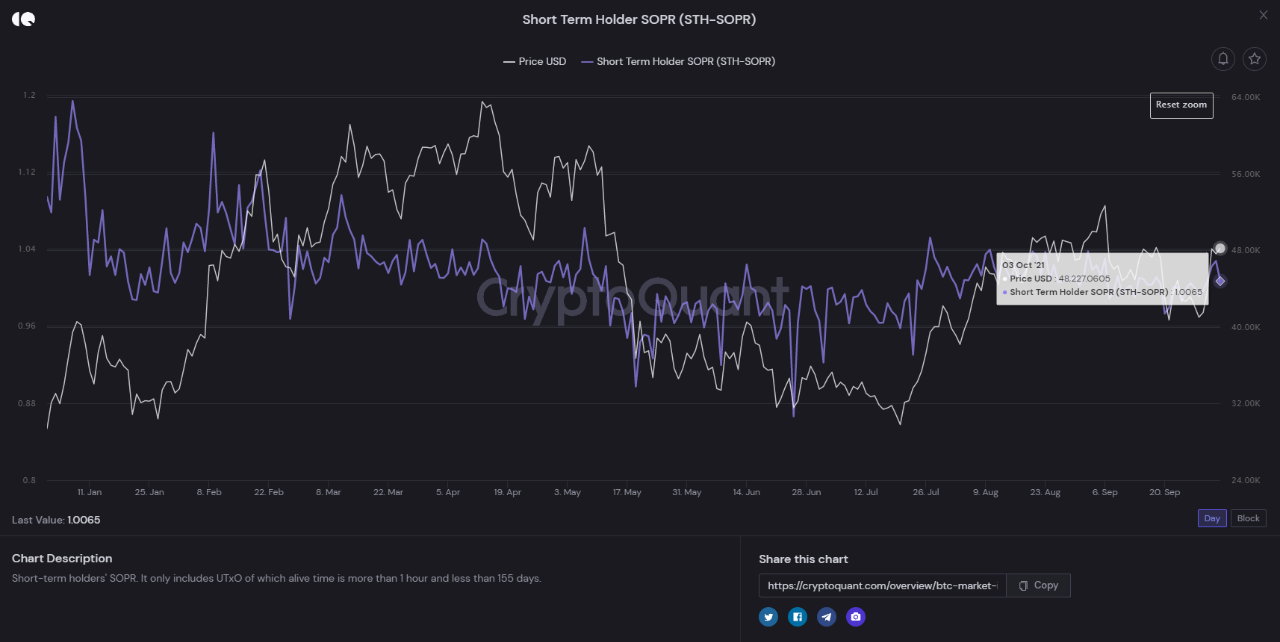
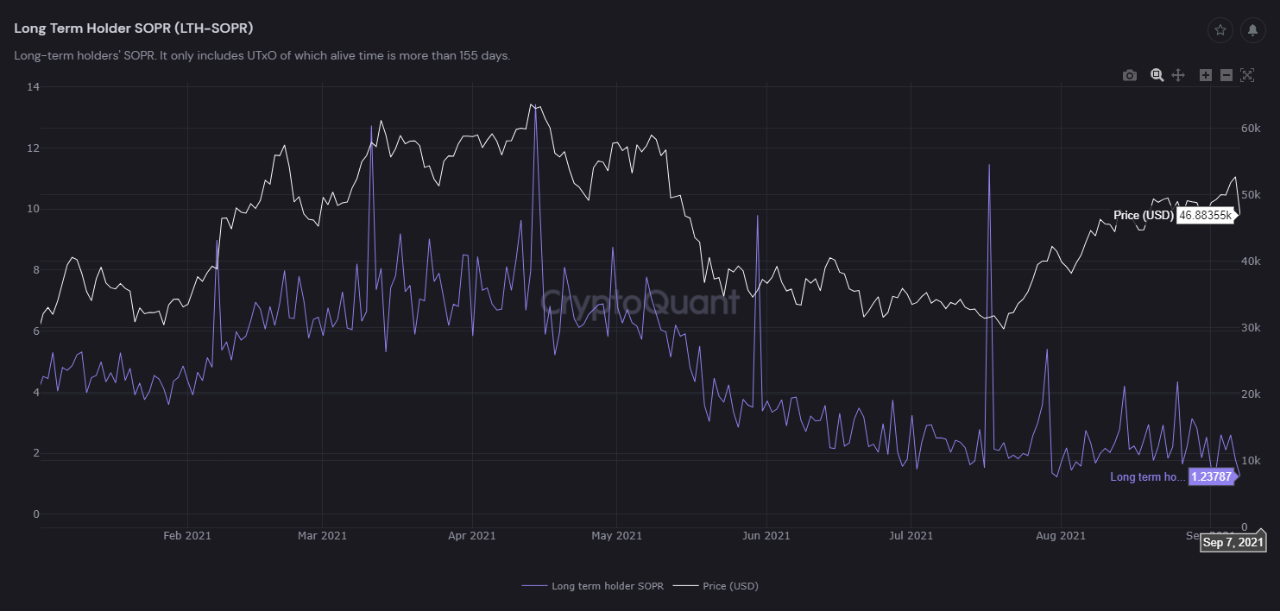
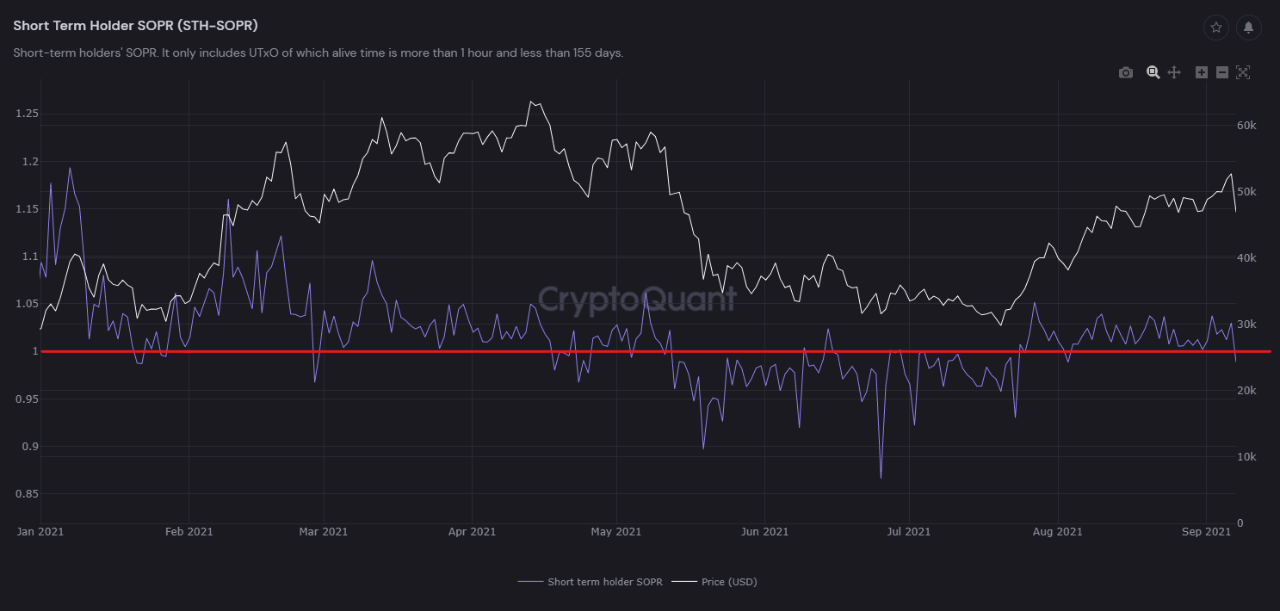
Spent Output Profit Ratio (SOPR) for both long-term (LTH) and short-term (STH) investors supports bullish price movements.
LTH-SOPR reset recently to 1.0, followed by an aggressive bounce. This usually happens at the end of bear markets / during pre bull markets.
STH-SOPR is positive and indicates a stop in profit taking (metric is not increasing further) and sufficient demand so that selling pressure can be absorbed.


View original →The recent flash crash in Bitcoin sent shockwaves across investors. On-Chain data, however, shows, that long-term holders (LTHs) seem unshaken by the shakeout of short-term holders (STHs).
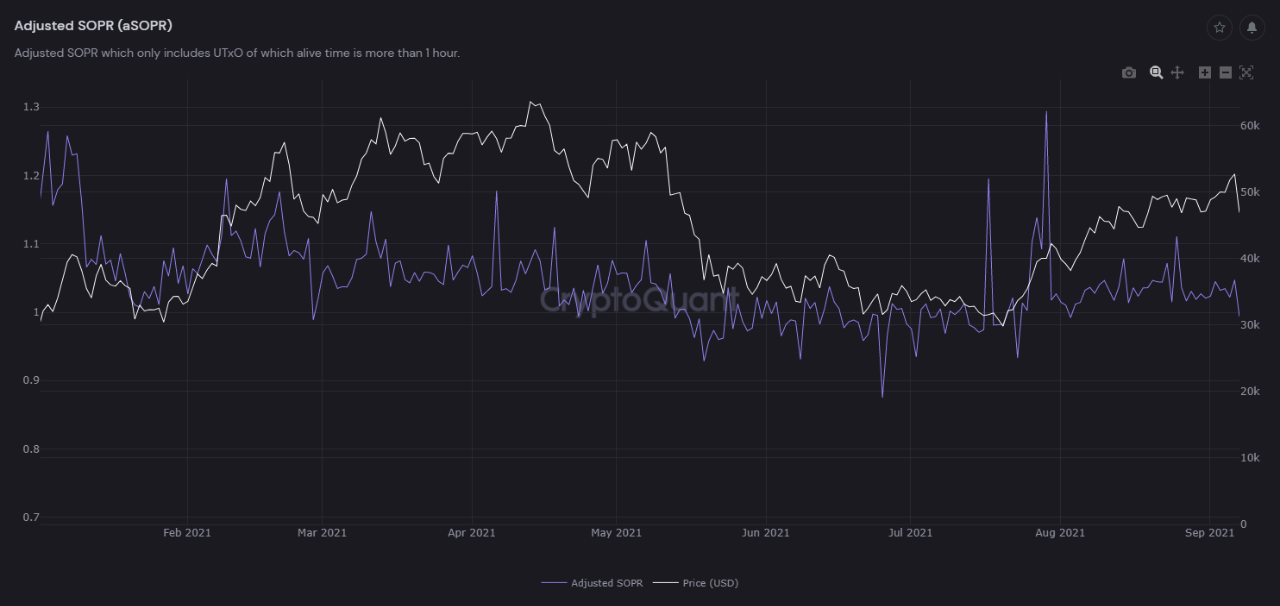
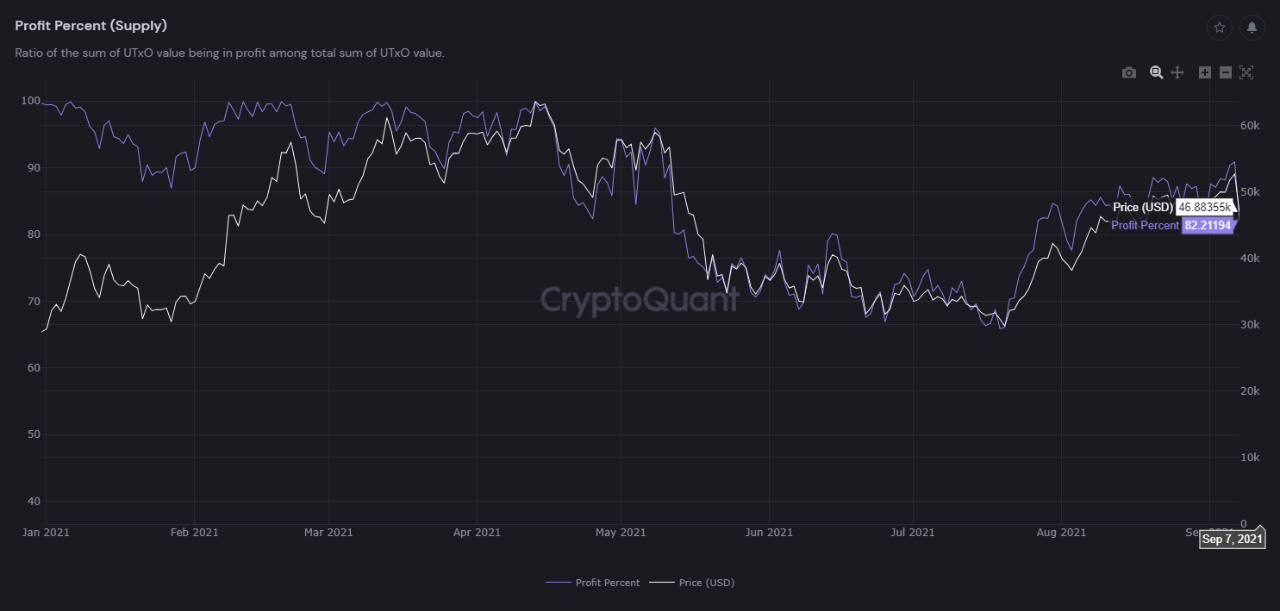
Similarly to the events in May 2021, we see the STH-SOPR below 1.0, which indicates BTC being spent at a loss. LTH-SOPR on the other hand remains above 1.0, same with the adjusted SOPR, while the total % of BTC supply remains above 80 %.
It was just a healthy shakeout, as far as presented data suggests

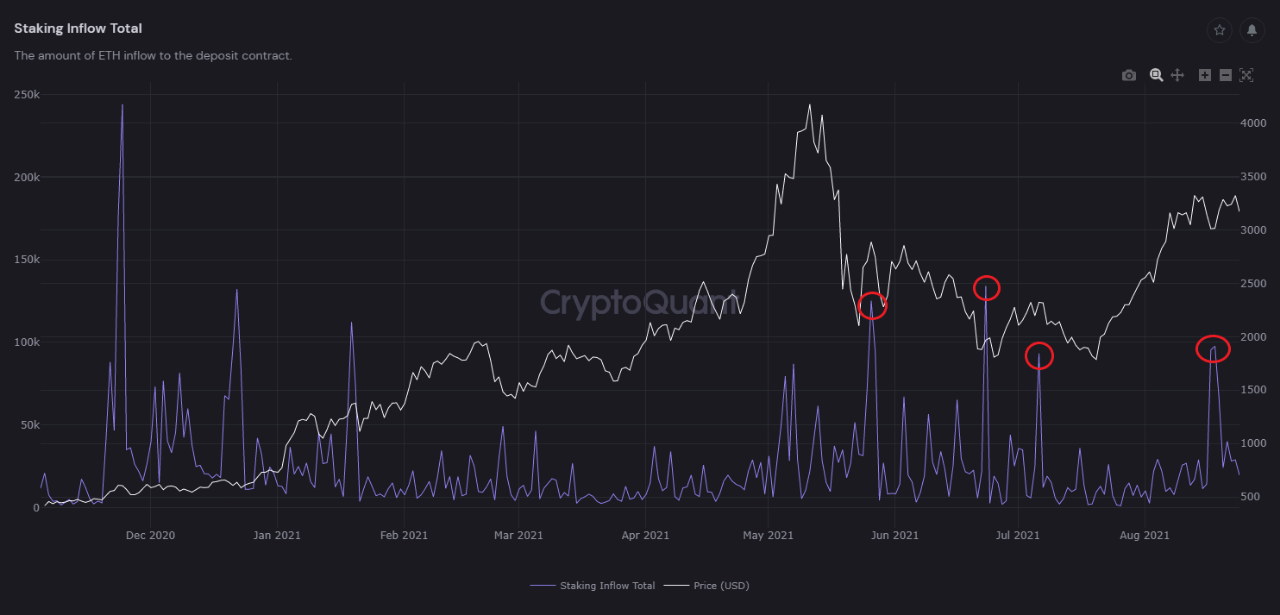
View original →...early ETH 2.0 Staking in cooperation with EIP-1559 burn. The more ETH gets locked in the deposit contract, the more ETH gets burned, the more likely we see a potential deflationary supply curve.
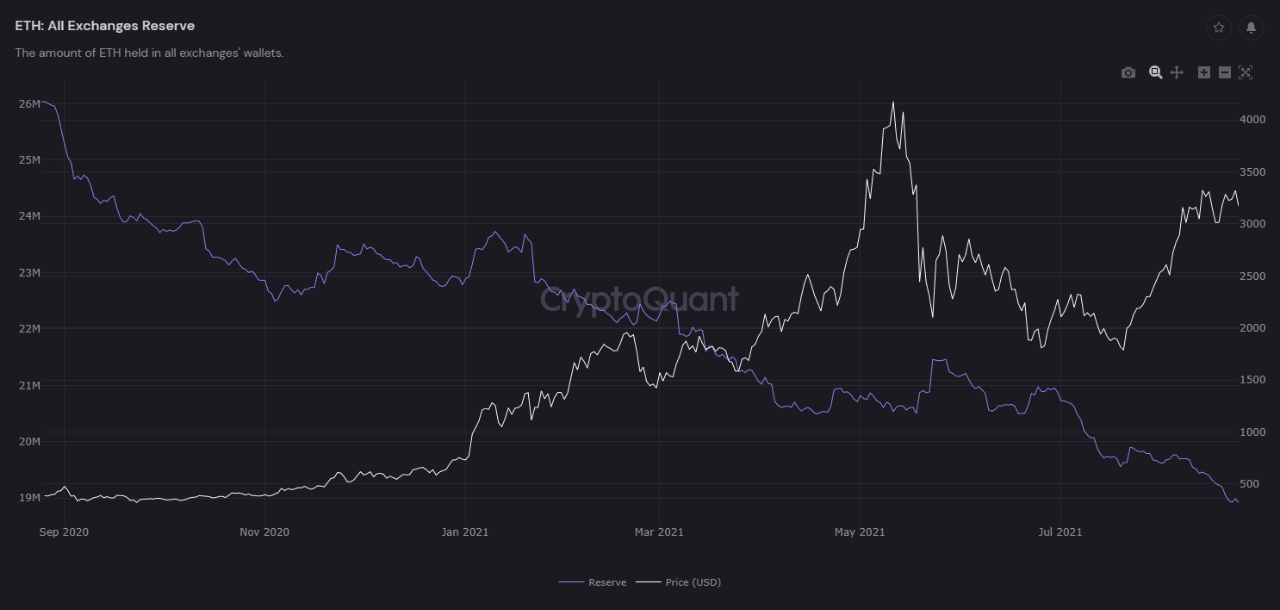
Relevant data looks nice. More than 7 million ETH are locked in Staking already, exchange reserves dropped strongly, and we see continued deposits even while Ethereum showed a strong signal of recovery from the lows during May and July 2021.


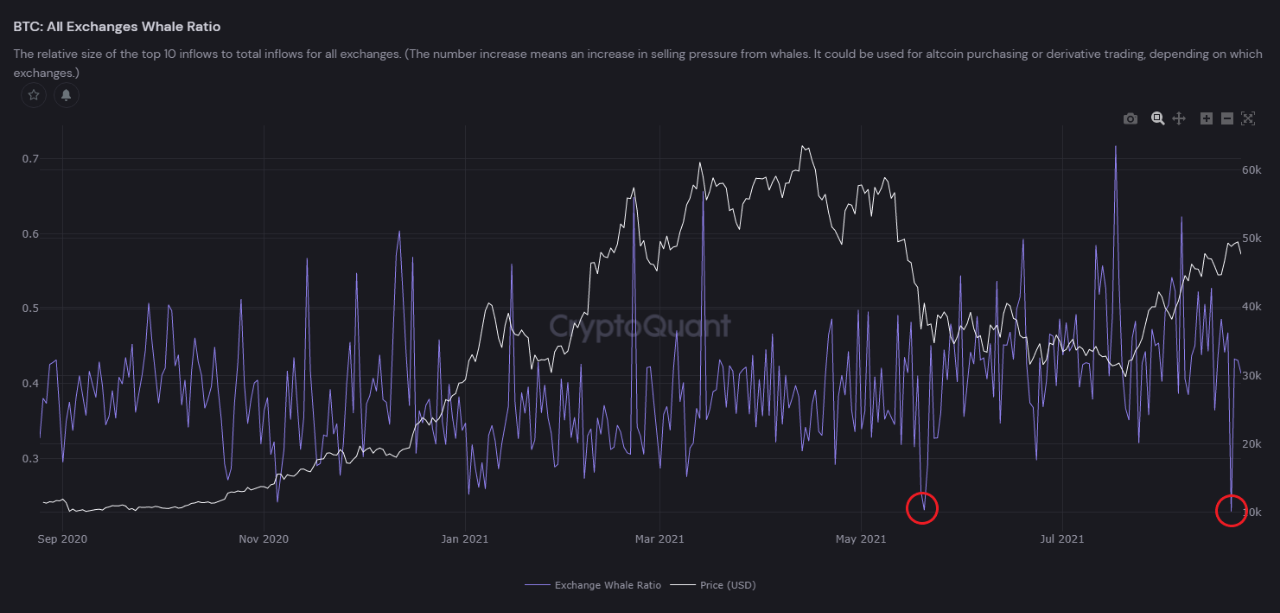
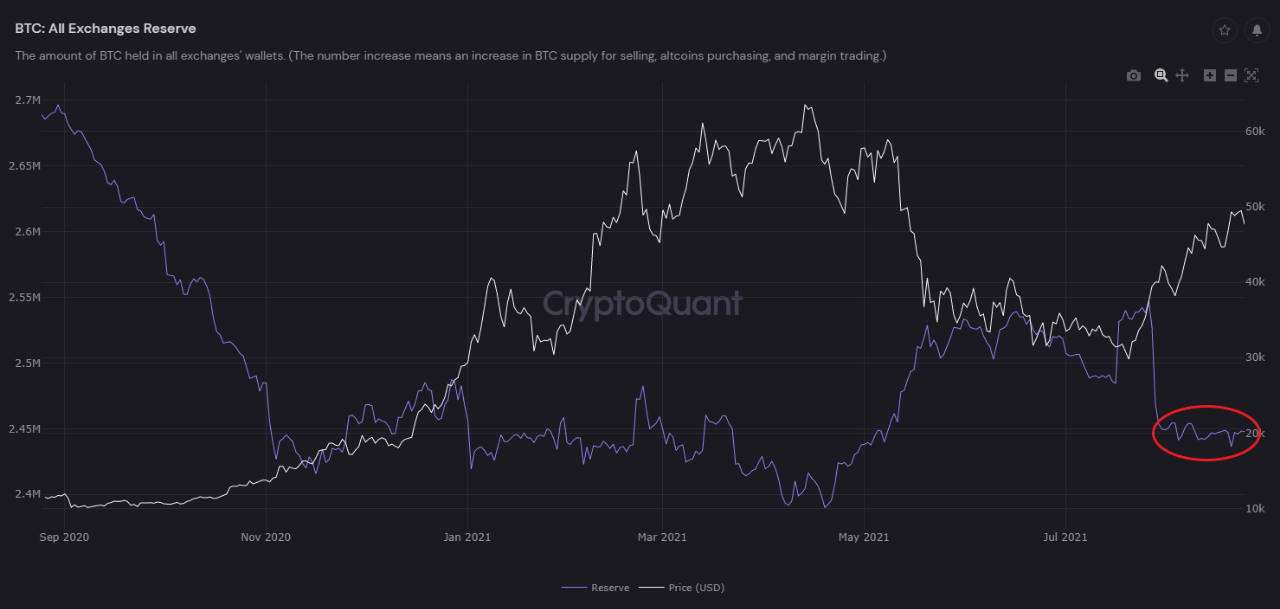
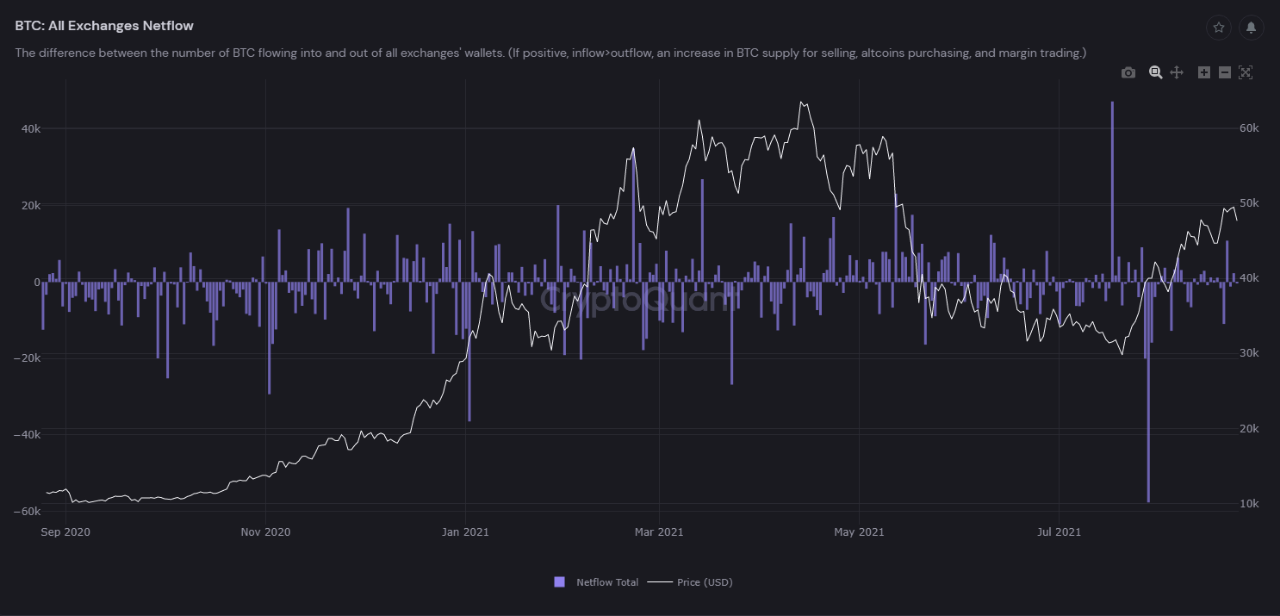
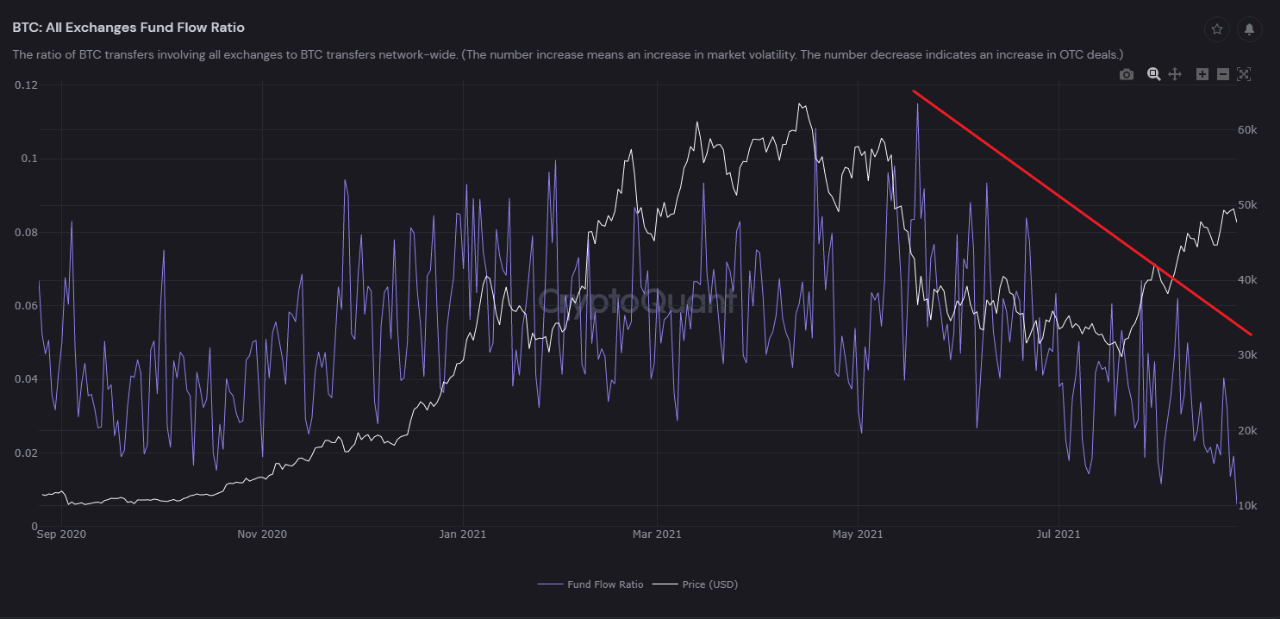
View original →BTC Whale Ratio fell and bounced aggressively in an event we saw last on May 20th. After the first event, we observed BTC being in what seemed like an accumulation phase for months.
All exchange reserves seem normal, net flows within ranges we expect. Fund flows on the other hand show a continued downtrend and consequently signal OTC deals. Lots of inflows to exchanges with custody solutions? Could be well just accumulated coins from OTC deals and Whales playing with the emotions of retail.

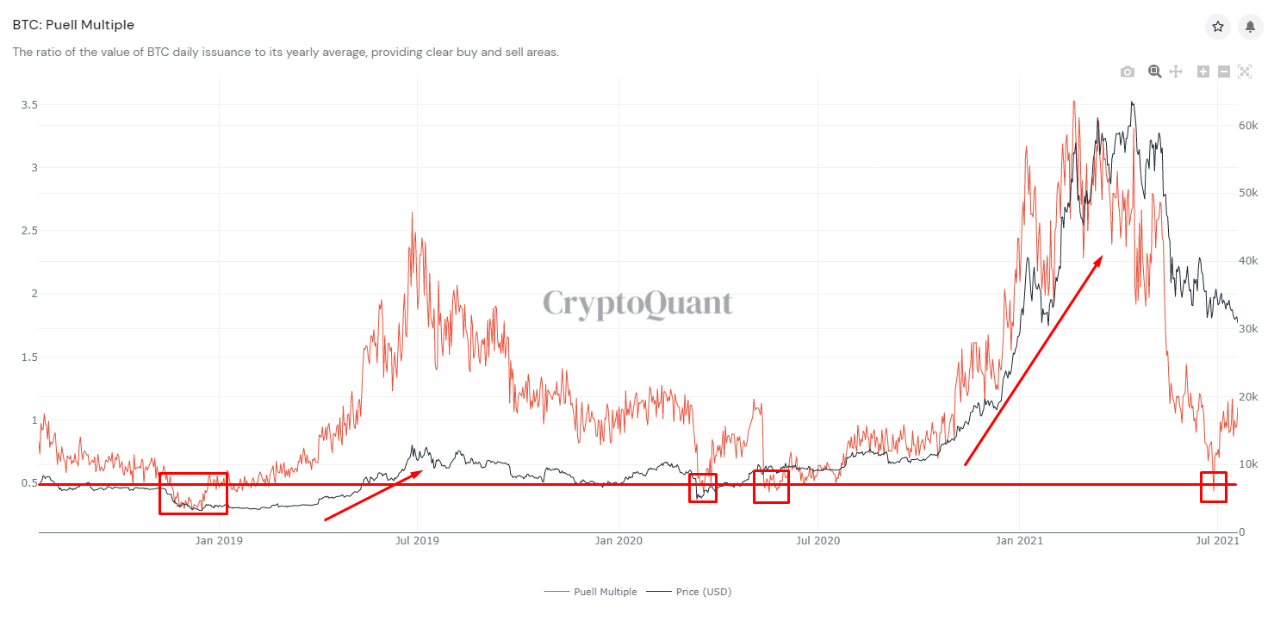
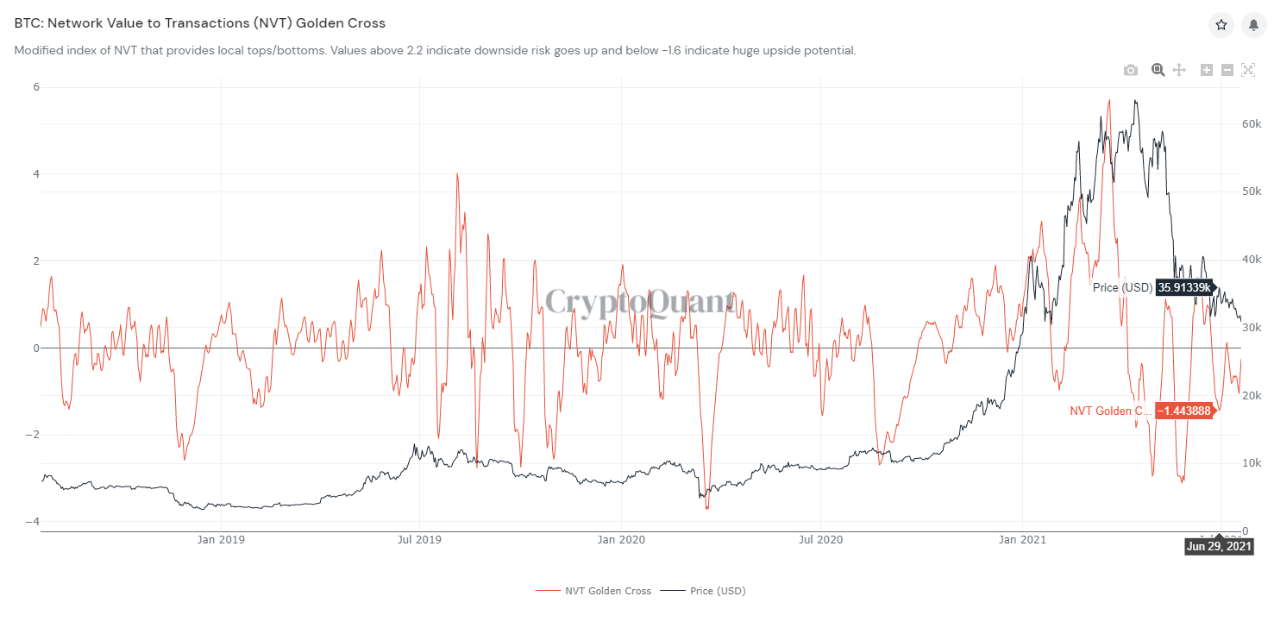
View original →Just as mentioned yesterday, I wanted to present some bullish signals next to the bearish ones. What I'm looking at is the Puell Multiple, which indicated upward rallies in the past decently. We recently fell below 0.5, which is the "buy zone". This comes with a NVT Golden Cross value close to the upside threshold recently.
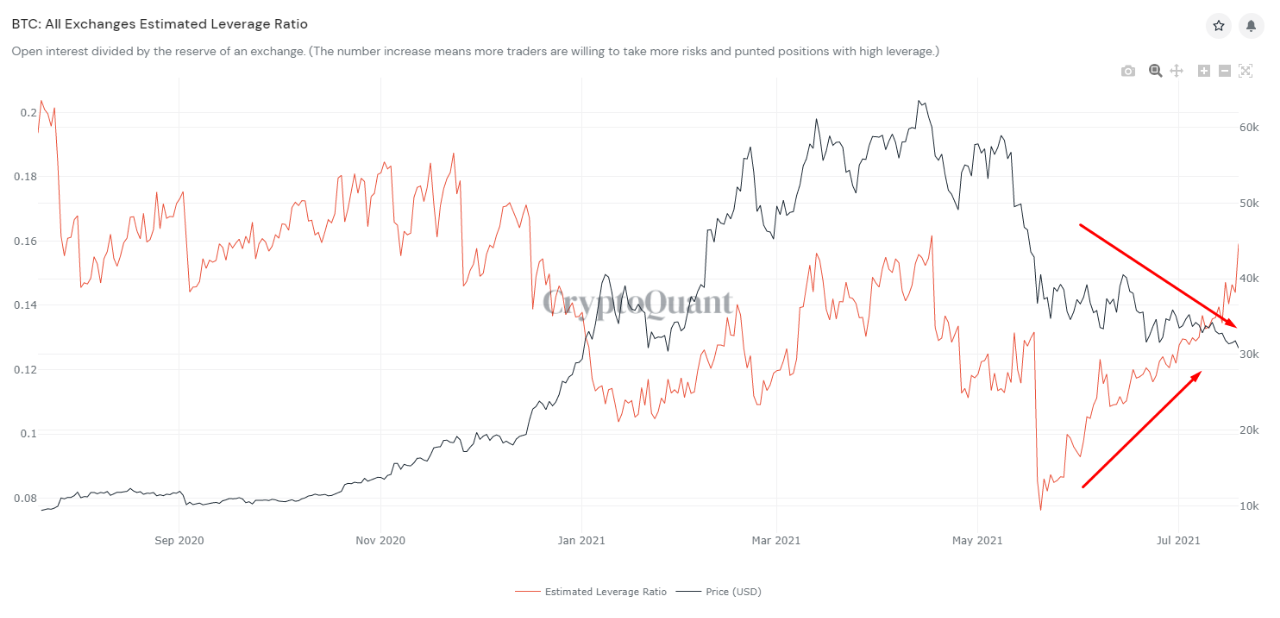
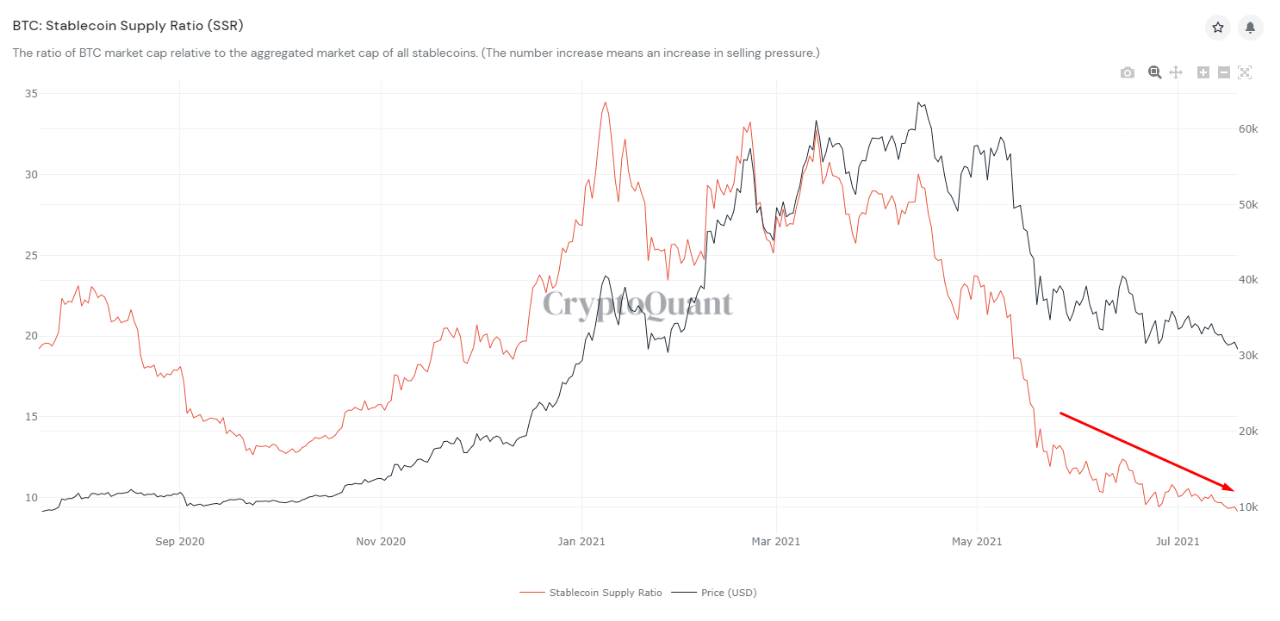
Leverage on exchanges is high, which leads me to believe that we will see a shakeout in over leveraged shorts soon. All while the SSR is still tending downwards.

View original →Bearish(Nuanced)BTC
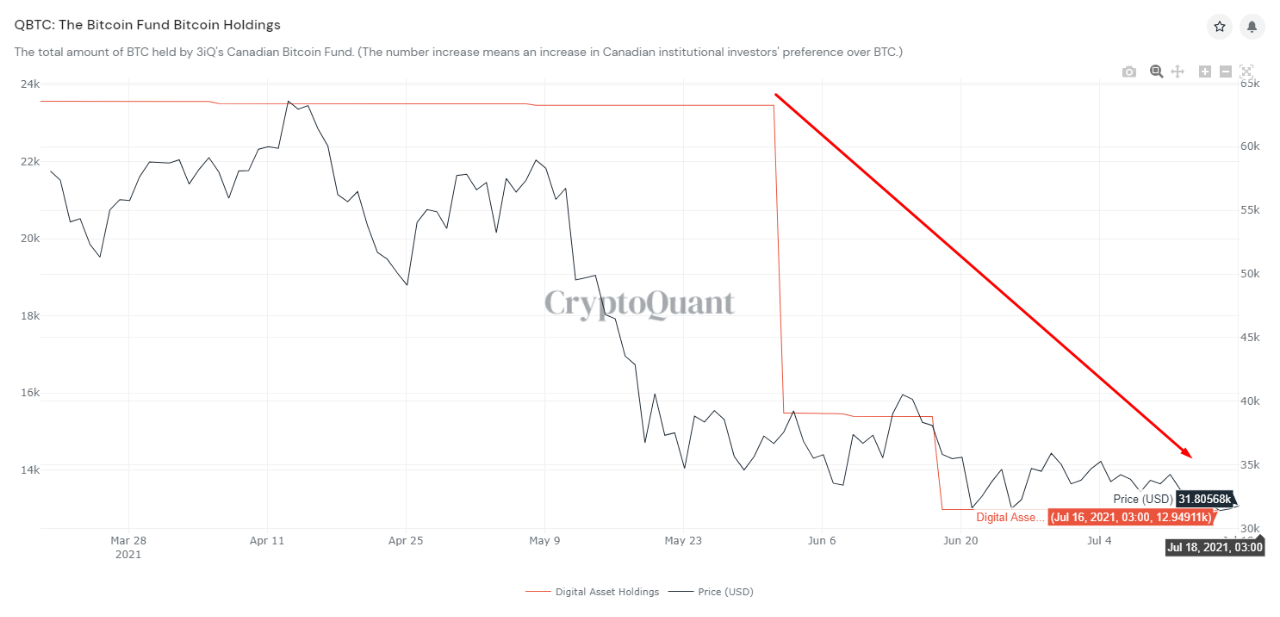
7/19/2021 When we look at On-Chain data and sentiment, we can clearly see that institutional demand remains low. GBTC discount continues with no imminent reversal signals. QBTC holdings fell sharply from more than 23k BTC in June to roughly 13k BTC.
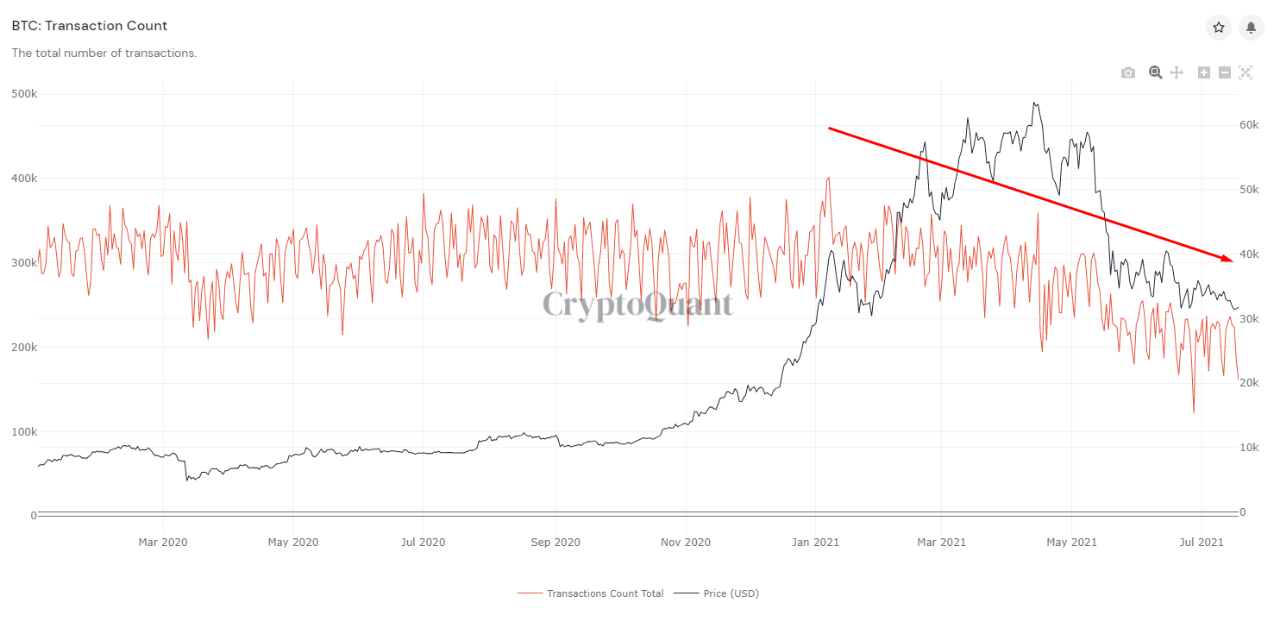
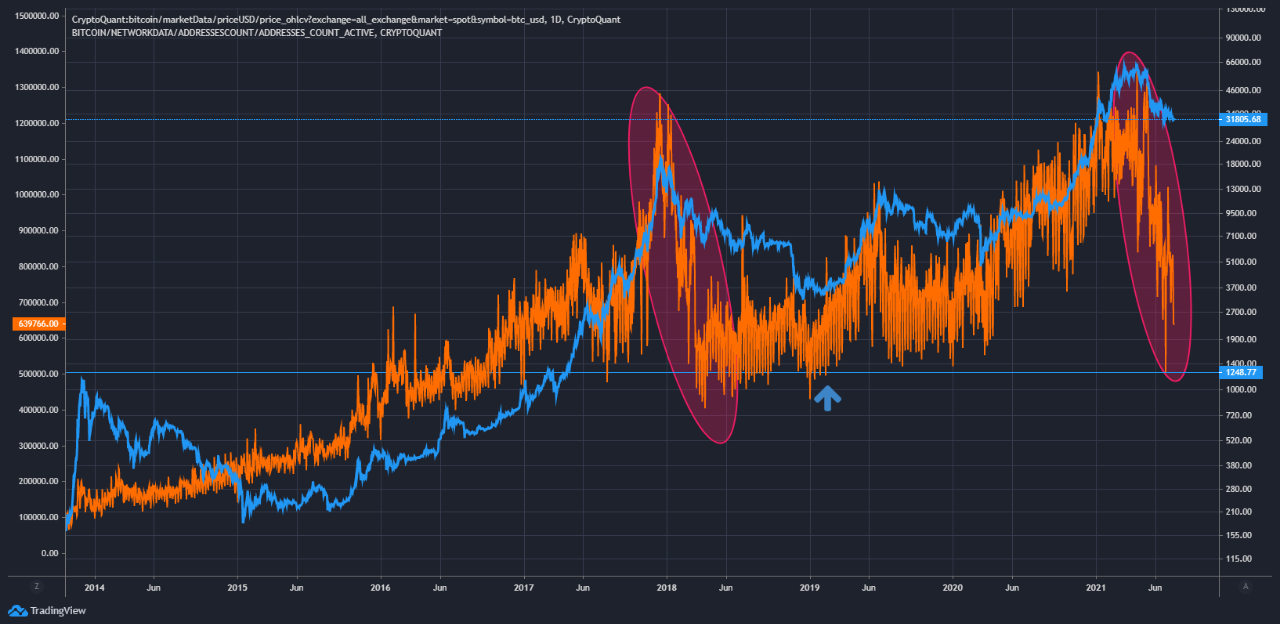
At the same time, we can see that the demand for transactions via Bitcoin network declines further (lowest demand since February 2019), while the network activity remains silent.
However, we see signs of accumulation! More on that in my next Quicktake.


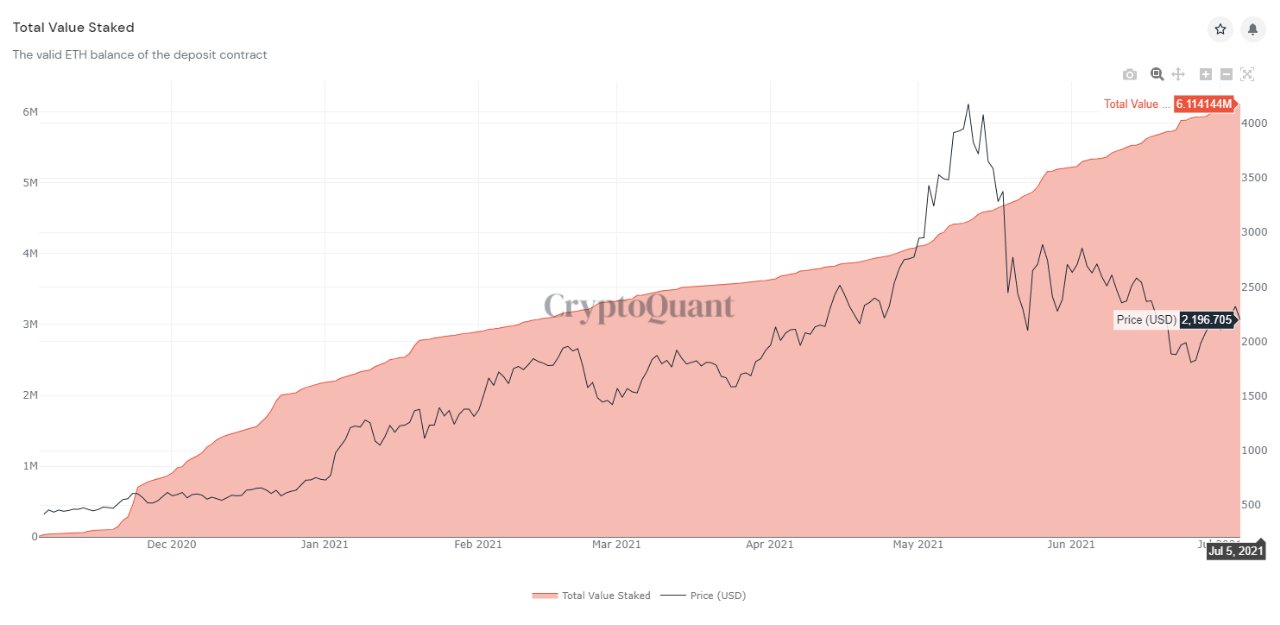
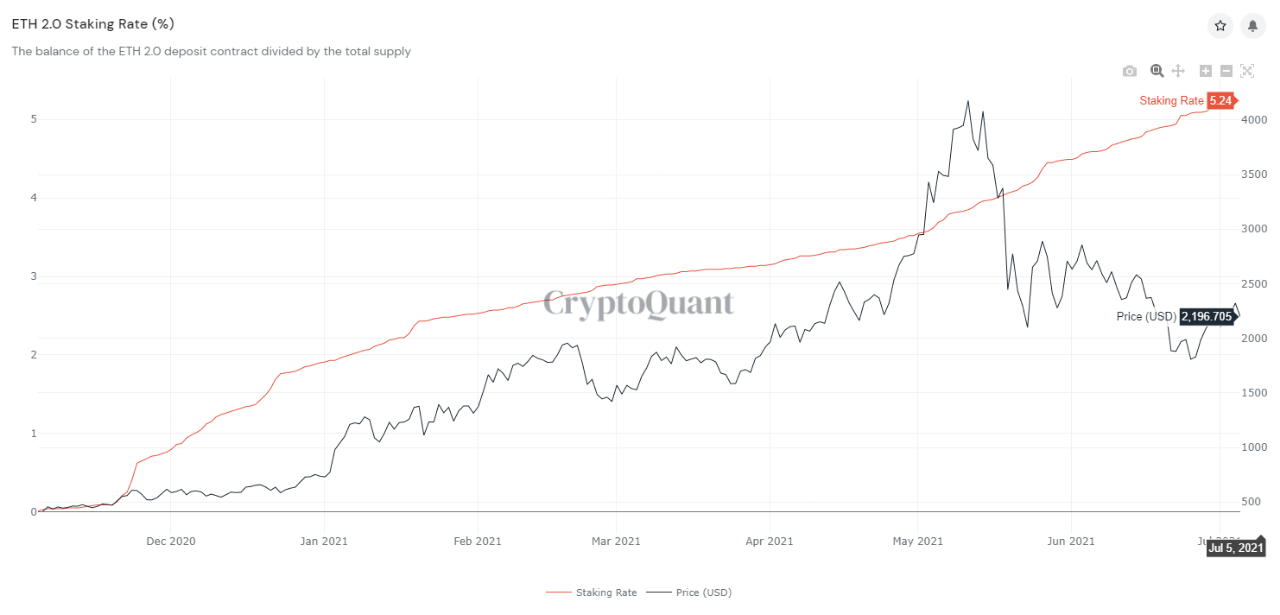
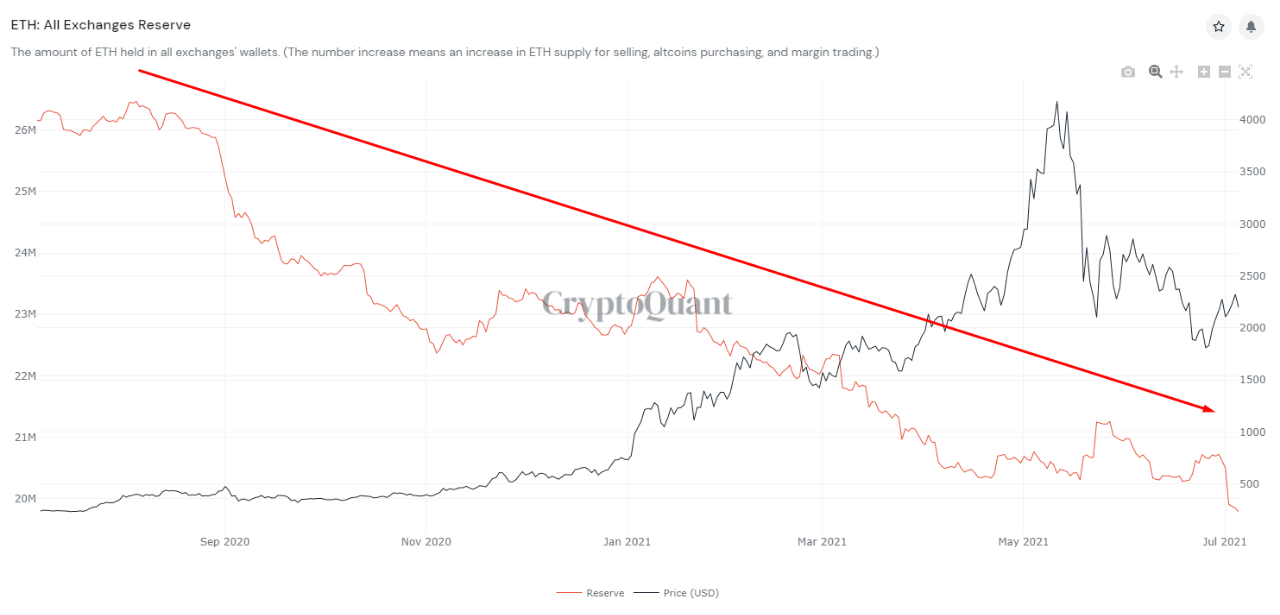
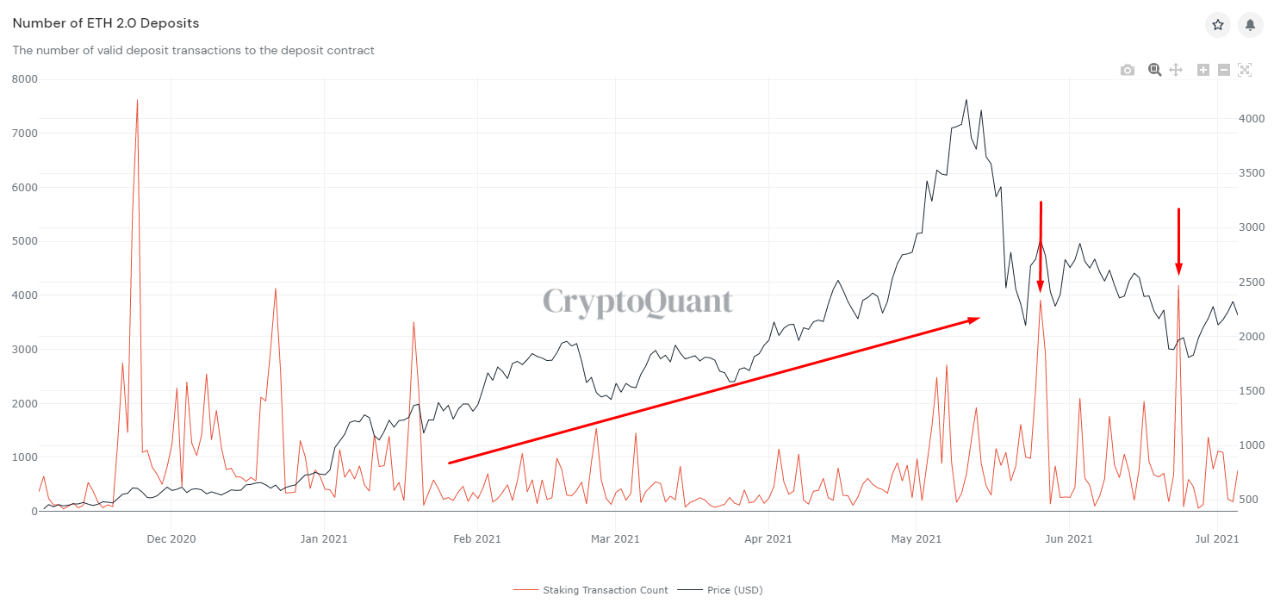
View original →When it comes to Ether's long-term performance, the success of Ethereum staking becomes more and more central (even more so than EIP-1559). And as we can see, investors choose to participate in early ETH 2.0 staking in an accelerating manner.
Total value staked is trending up, more circulating supply gets locked-up in the ETH 2.0 deposit contract. All exchanges reserves is declining further, while investors seem like they used cheap Ether to deposit to the ETH 2.0 deposit contract recently.

View original →Bullish(Nuanced)ETH
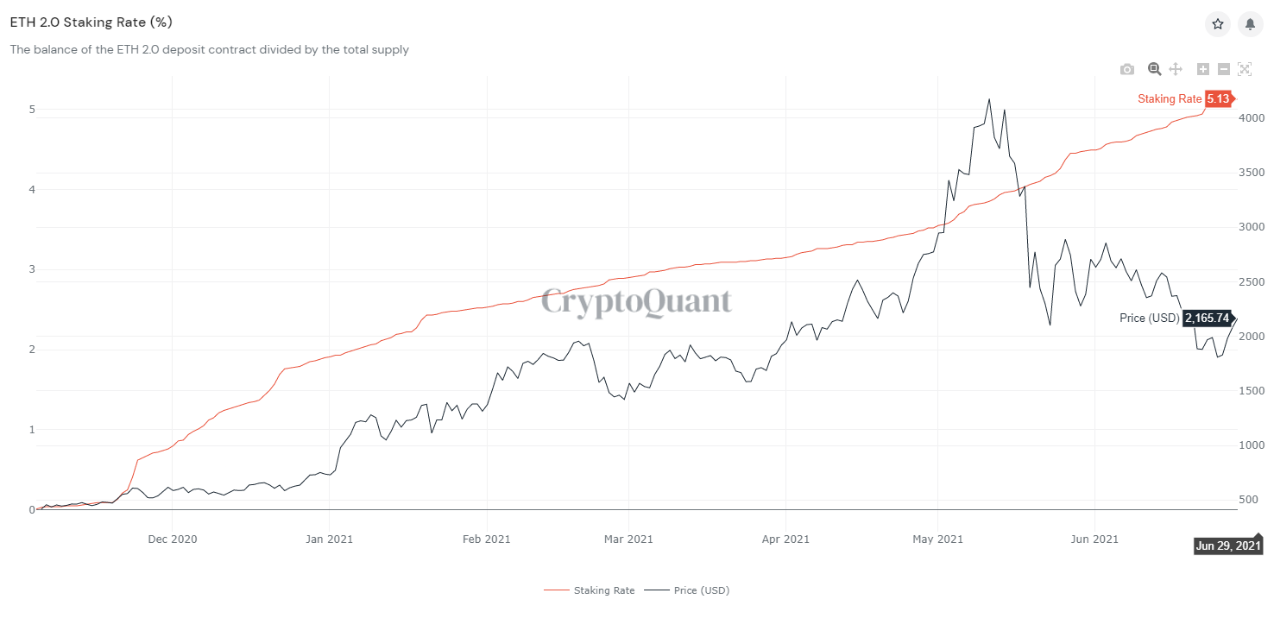
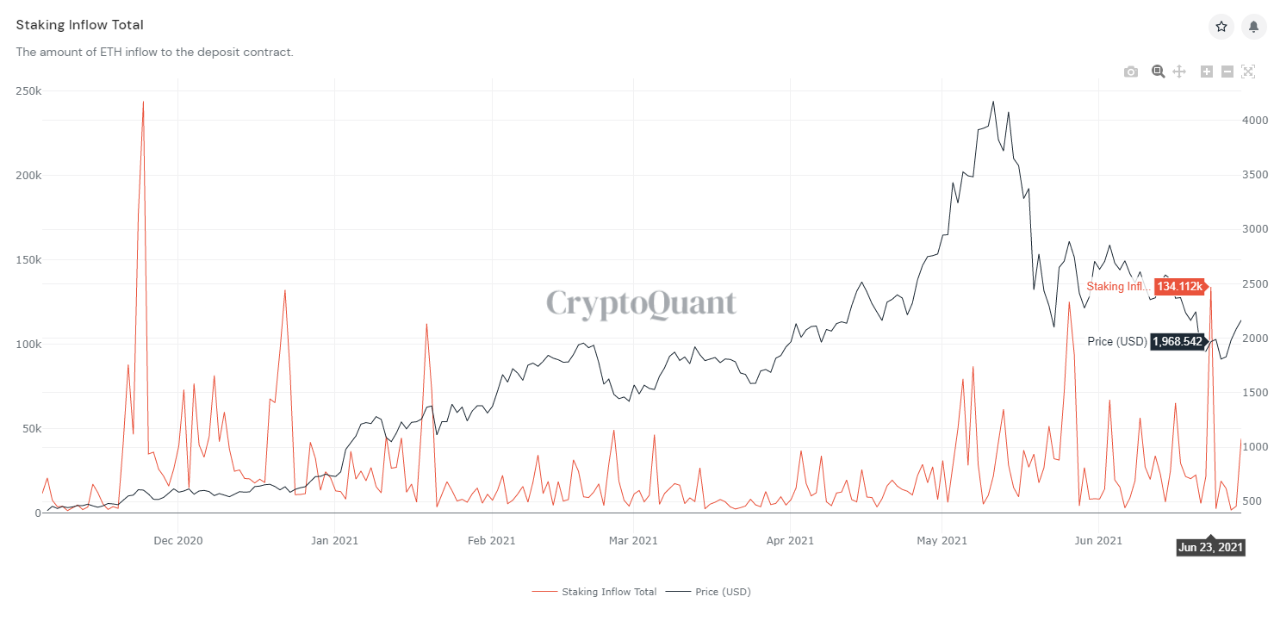
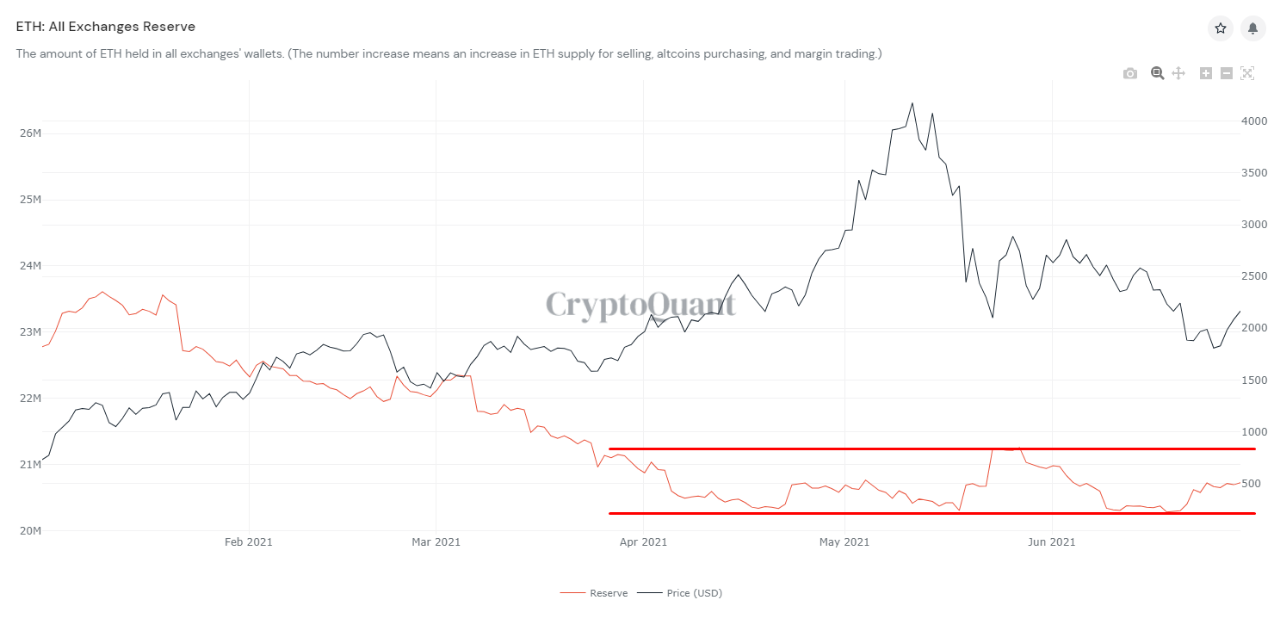
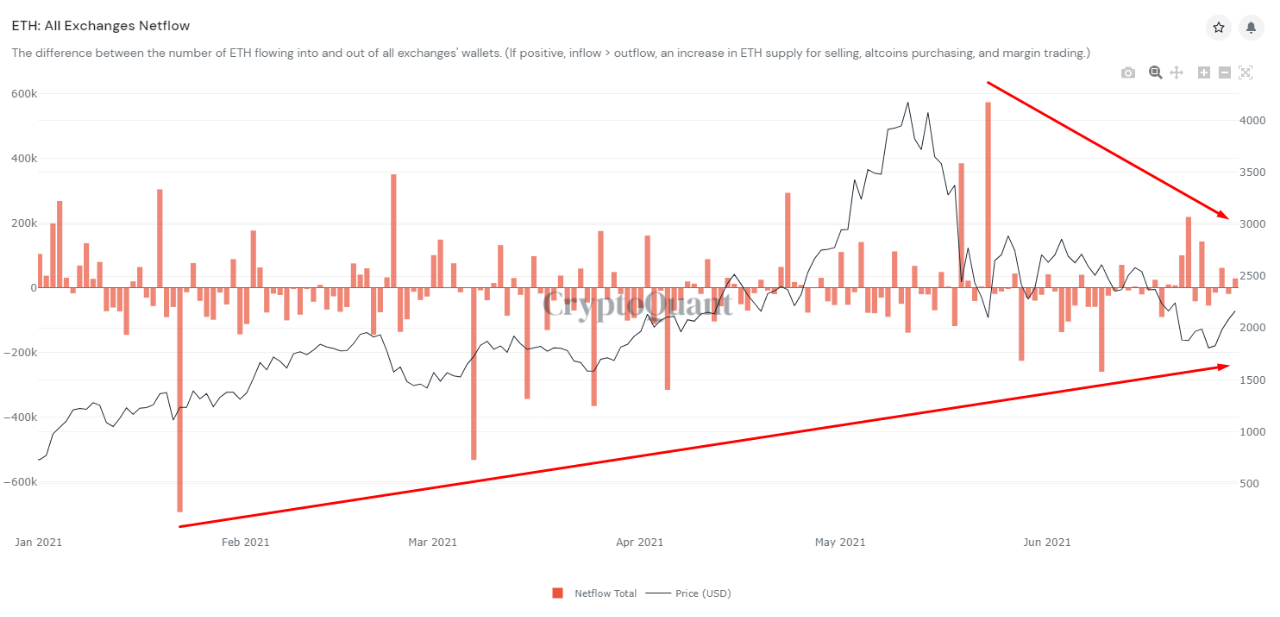
6/30/2021 While the Ethereum price is still range-bound on the market, data shows that ETH is getting locked up long-term with several large inflows to the ETH 2.0 deposit contract. More than 5 % of the circulating supply are already locked in staking and thus illiquid.
Paired with sideways movement in the ETH reserves (all exchanges) and decreasing net flows, it looks like ranging will go on for a while, still, but the long-term outlook remains positive despite prices oscillating at critical levels.

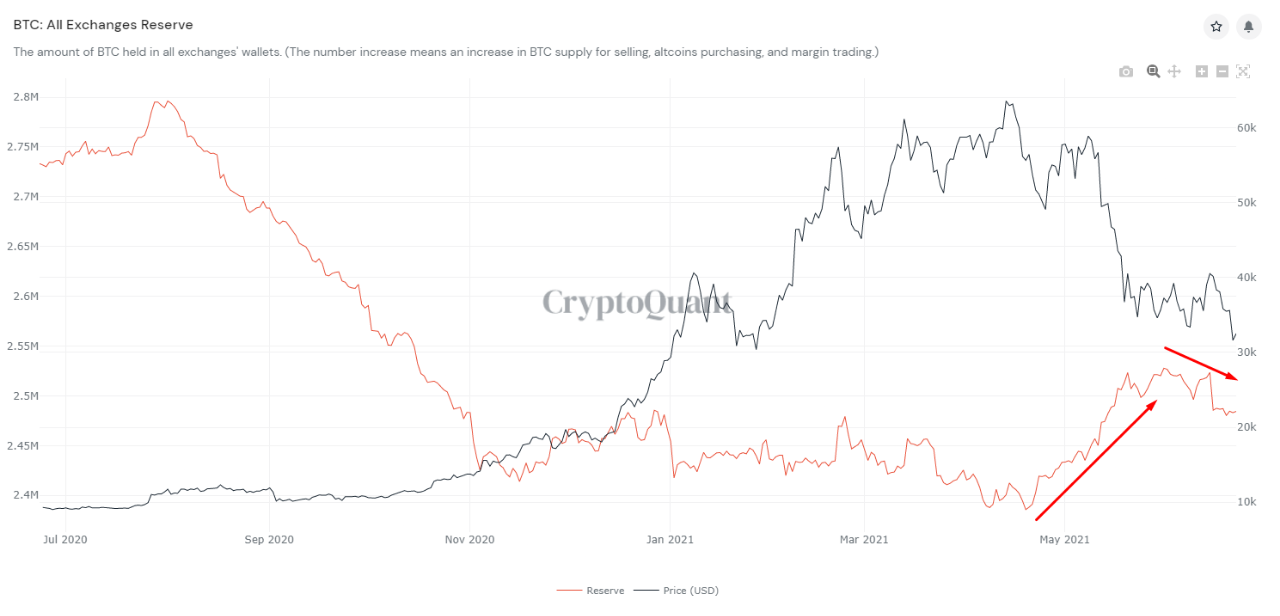
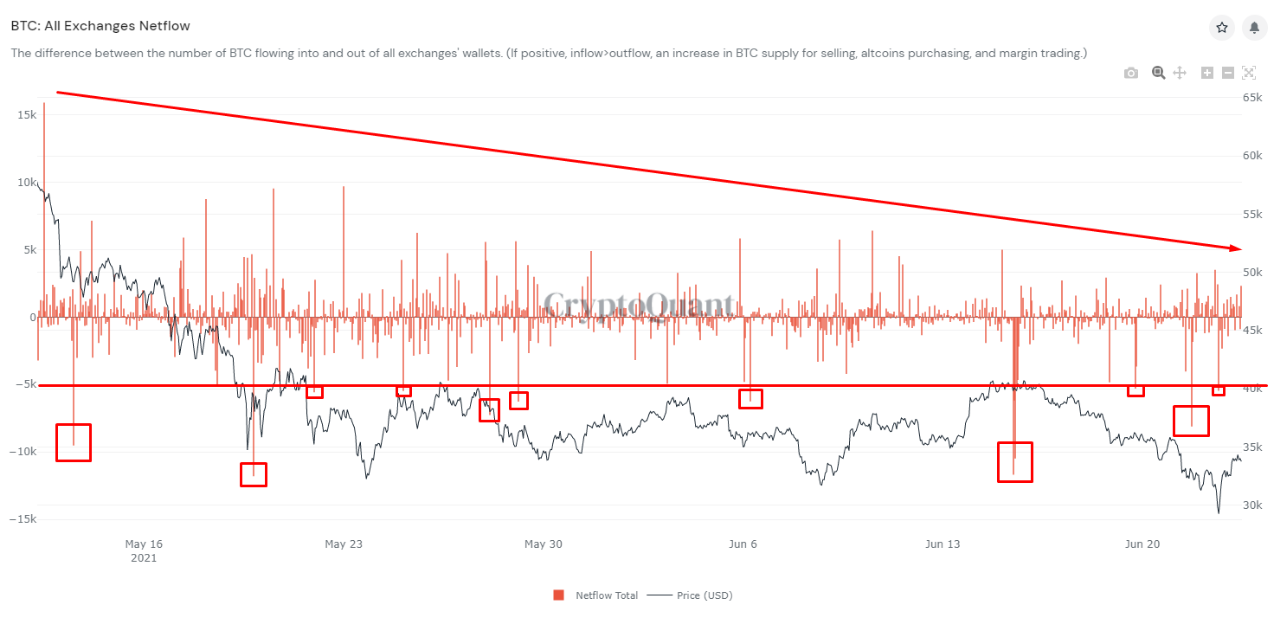
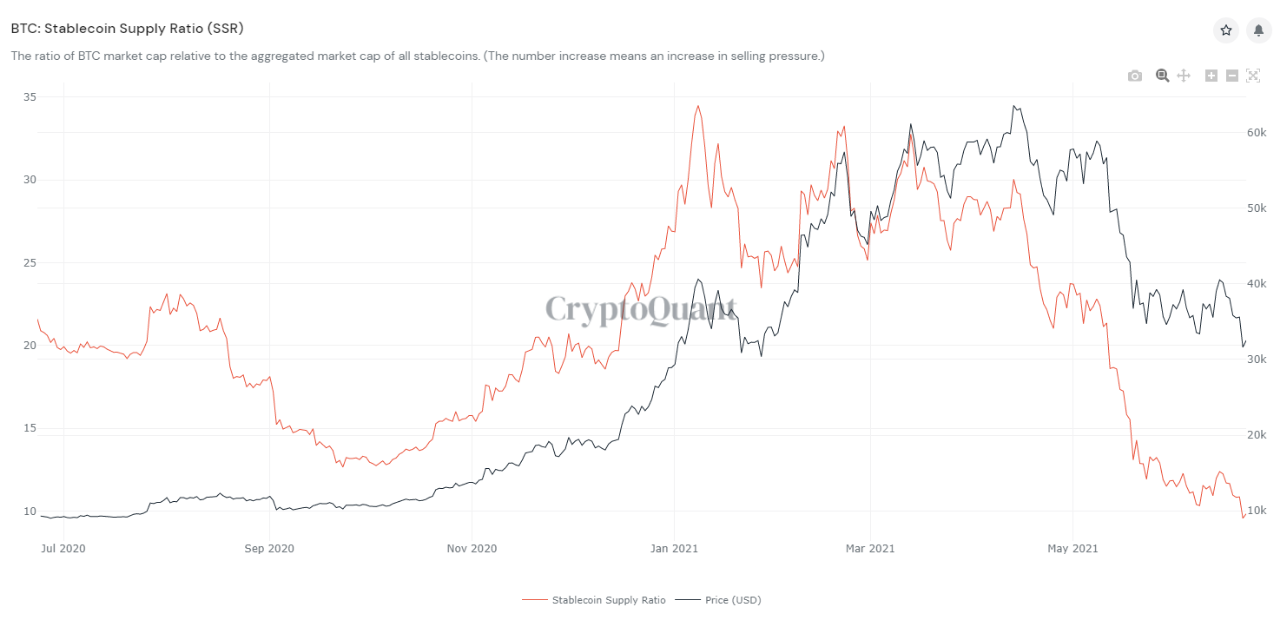
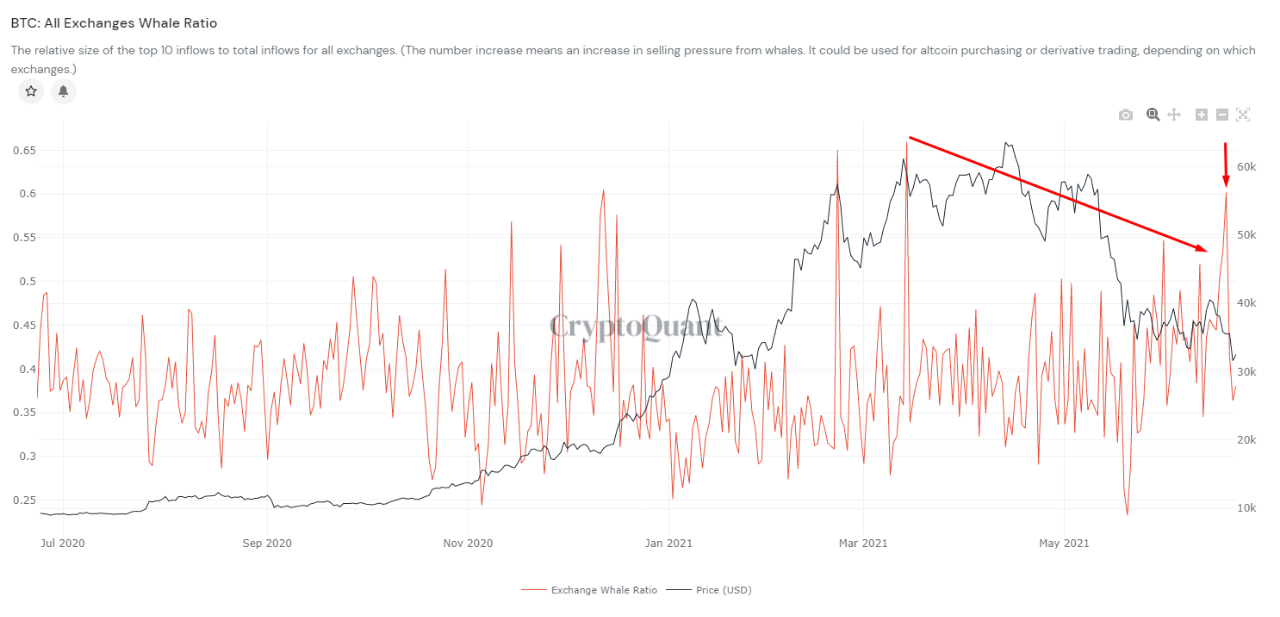
View original →Narratives about a multi-year bear market grow stronger, especially since Bitcoin dropped below $30k, temporarily. But looking at BTC reserves across all exchanges, we can see that the amount of BTC on exchanges drops again. At the same time, Net Flow shows accumulation of more than 5k multiple times within hours.
Together with a low SSR (more buying power on the sidelines) and an overall declining Whale ratio (one exception), the case for a multi-year bear market seems to be fragile.

View original →Bearish(Nuanced)BTC
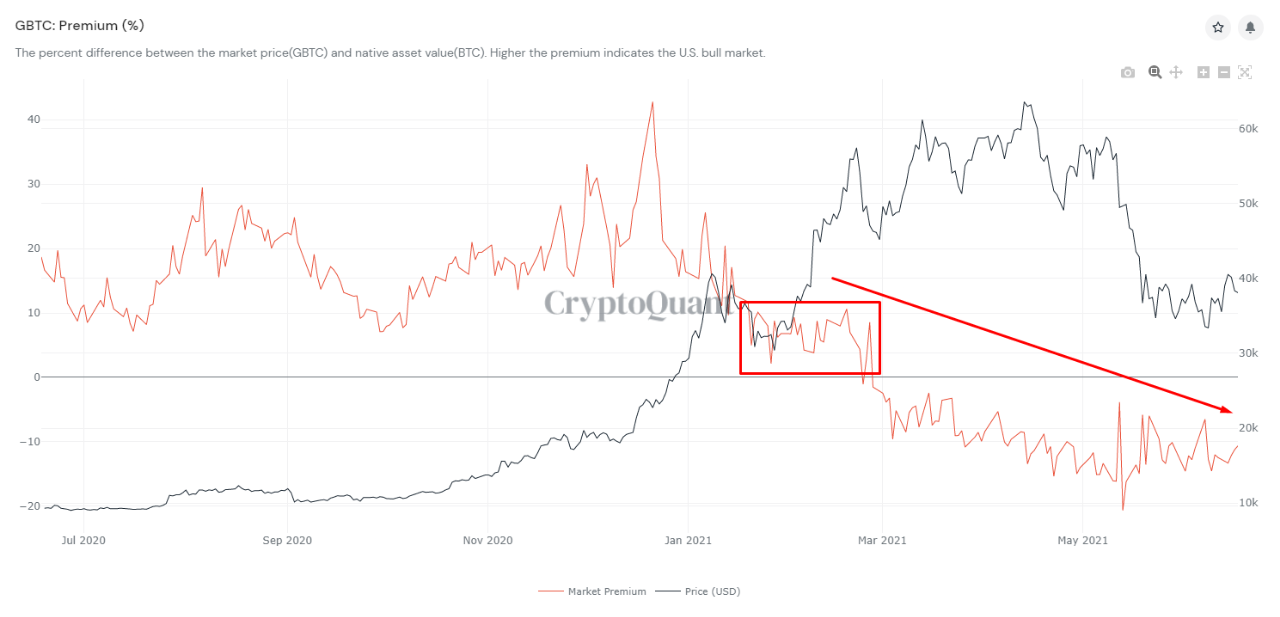
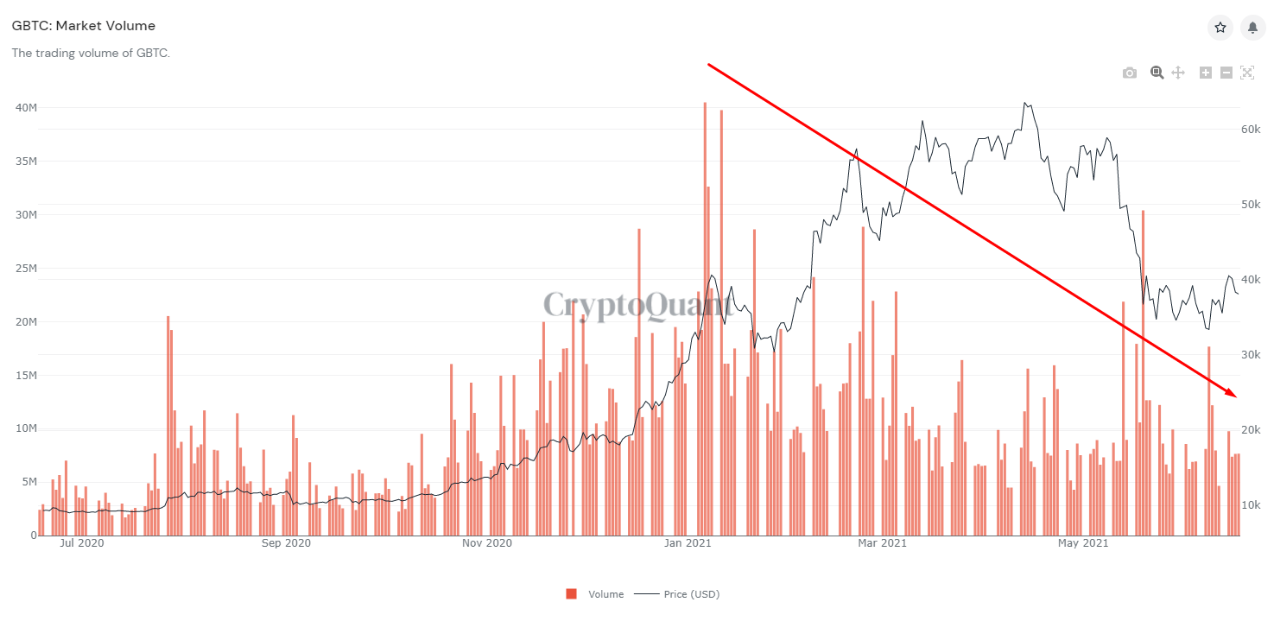
6/18/2021 Despite a discount in the Grayscale Bitcoin Trust (GBTC) since late February, institutional demand for Bitcoin declined. The rise from ~ $58350 all the way to the current ATH was mostly retail-driven.
If we speculate on a strong reaction from the price and a breakout above $42k towards $50k, we better see demand from the main driver behind the bull run up to ~ $58350: institutional money. Regulatory uncertainty and a stronger USD don't favor institutional investors' interest.


View original →

